Real estate and mortgage under one roof
Welcome to California!
Free consultation — call today
(949) 404-0054
Home Home Loans Commercial For Professionals Buying a House Area Guides Selling a House Real Estate Tax Strategies Calculators Reviews News Contact

Alavi Home Loans · Real Estate & Mortgage Under One Roof

Buy or sell a home and finance it — all under one roof. Save thousands.

I'm Farzad Alavi — your real estate agent and your mortgage loan officer in one. No juggling two people at two different brokerages: one plan, less hassle, lower closing costs, and credits that can lower your interest rate — often saving you thousands. Home-loan guidance throughout California, plus investment property financing nationwide across the United States.

Luxury Newport Beach coastal estate framed by palm trees at sunset
Farzad Alavi
Farzad Alavi Licensed Mortgage Broker & Real Estate AgentOne clear plan for the property and the loanI’m here to help—call or text me anytime.

Southern California focus · California-wide help

Start with a no-pressure conversation.

Farzad specializes in Orange County, Los Angeles, San Diego, and Southern California, and can help anywhere in California—including Northern California—with trusted agents across the state. Just send him a text with any question and he will help you find the next step.

Text Farzad any question

A simple place to start

Find your loan in 60 seconds.

No mortgage knowledge needed. Choose what sounds like you, and we’ll narrow down the options together.

Four short steps Plain-language answers No obligation
Or browse all loan programs →
Step 1 of 4Your goal

What do you want to do?

There’s no wrong answer—just choose the property you have in mind.

Not sure which loan fits your situation?
Ask your licensed California loan officer: (949) 404-0054

Your first home, one clear step at a time

You do not have to know mortgages to get started.

Buying your first home can feel like a lot. Farzad will explain the choices in plain language, help you understand what you can comfortably afford, and stay available when questions come up.

Down payment assistance

Qualified buyers may be able to combine a first mortgage with a grant, deferred-payment loan, or repayable second loan to reduce the cash needed upfront. The right option depends on income, location, household, property, and available program funds.

CalHFA programs

Eligible California buyers may be able to pair an approved first mortgage with CalHFA down-payment or closing-cost assistance. Income limits, homebuyer education, repayment terms, program availability, and property rules apply.

FHA low down payment

FHA financing can offer a lower down payment and more flexible qualifying rules for an eligible primary home. Mortgage insurance and property standards apply, so Farzad explains the complete monthly and upfront cost.

Help with closing costs

Depending on the loan and transaction, closing costs may be helped by an assistance program, an allowed seller credit, a lender-credit option, or eligible gift funds. Farzad will show what each choice changes before you make an offer.

Possible tax benefits

Homeowners may qualify for deductions related to mortgage interest or property taxes, depending on their situation and current tax rules. A qualified tax professional can explain which benefits apply to you.

First-buyer education

Some assistance programs require an approved homebuyer course. Even when it is optional, the education can make budgeting, inspections, insurance, escrow, and closing easier to understand.

Programs and benefits are not automatic, and not every option can be combined. Farzad can compare what is currently available for your income, location, credit, and purchase plan.

STEP 01

Start with your budget

Look at a monthly payment that feels comfortable, not only the highest amount a lender may approve.

STEP 02

Understand the down payment

You may not need 20% down. The right amount depends on the loan, your savings, closing costs, and the cushion you want to keep.

STEP 03

Get pre-approved

A pre-approval reviews your income, credit, savings, and debts so you can shop with a realistic price range. It is not a final loan approval.

STEP 04

Shop and close with guidance

Once you find a home, the lender reviews the property and your final documents before closing. Farzad helps you understand each milestone.

Questions are welcome. Text or call before you are ready to apply. A short conversation can help you understand the next step without pressure.

Buying your first home and want someone to explain it all simply?
Talk to a licensed mortgage broker: (949) 404-0054

Credit guidance for future homebuyers

Your credit does not have to be perfect—and you do not have to fix it alone.

A credit score is a number, usually from 300 to 850, that helps lenders understand how you have handled borrowed money. Farzad works directly with people who are not mortgage-ready yet: he reviews the situation with you, helps map the practical steps that may raise your score over time, and stays available as you work toward qualifying for a home loan.

Excellent800–850Strong credit history and typically the broadest financing choices.
Good670–799Often supports competitive mortgage options, depending on the full application.
Fair580–669Some loan options may still be available, with closer review of the full file.
Poor300–579A step-by-step improvement plan may help you prepare before applying.

Why your score matters

Your score is not the only part of a mortgage decision, but it can affect which programs are available, the interest rate and mortgage-insurance cost you may be offered, and how confidently a lender can approve the file. Income, debts, savings, down payment, and the property matter too.

Payment history
Whether payments were made on time. This is usually the most important part.
Amounts owed
How much of your available credit you are using, especially on credit cards.
Length of history
How long your accounts have been open and active.
New credit
Recent applications and newly opened accounts.
Credit mix
Experience managing different kinds of accounts, such as cards and installment loans.

Practical ways to improve over time

Pay on time

Set reminders or automatic payments so due dates are not missed.

Lower balances

Reducing credit-card balances can lower the amount of available credit you use.

Keep older cards open

Closing a long-held card can shorten your history or reduce available credit.

Limit new applications

Apply only when needed while you are preparing for a mortgage.

Check for errors

Review all three credit reports and dispute information that is truly inaccurate.

Want to know more about what your credit score means for your mortgage?
Ask your loan officer — free consultation: (949) 404-0054

Home loans for independent income

Your tax returns may not tell the whole story.

If your tax returns do not show your real income, there are loans designed for you. Irregular income—or income that comes through your own business—does not automatically disqualify you from buying or refinancing a home.

Business owners, freelancers, independent contractors, gig workers, and cash-income earners: Farzad can begin with the records you actually have and explain which path may fit.

01

Bank statement loans

A lender may review 12 or 24 months of eligible personal or business deposits to estimate qualifying income instead of relying only on tax returns. Business expenses, deposit patterns, credit, assets, and reserves still matter.

02

P&L-only programs

Some programs may use a current profit-and-loss statement prepared by an accountant to show how the business is performing now. The lender will still review the full loan, property, credit, funds, and ability to repay.

03

1099 income programs

Freelancers and contractors may be able to qualify using consistent 1099 earnings rather than full tax returns. Work history, income stability, deductions, down payment, and program rules help determine the fit.

Cash income still needs a clear, acceptable paper trail, but it does not have to look like a regular paycheck. Farzad can review your bank statements, P&L, 1099s, or other available records and help you choose the strongest starting point.

Self-employed and wondering how to show your real income?
Ask your licensed California loan officer: (949) 404-0054

Southern California area guides

Start with the life you want, then choose the address.

For families relocating to Orange County, buyers moving to California with kids, and people arriving from outside the United States, a city name is only the beginning. Compare daily routines, school boundaries, commute direction, community feel, and the relative cost of different areas before you narrow the home search. Farzad provides mortgage guidance across Orange County, Los Angeles, and San Diego, while his direct real estate representation is concentrated in Orange County.

Local mortgage guidance

Loan officer help across Southern California

Searching for the best loan officer in your city usually means looking for someone who listens, explains the full cost, and can match the paperwork you actually have to the right loan path. Farzad Alavi provides mortgage guidance across Orange County, Los Angeles, and San Diego; “best” is personal, so start with a conversation and decide whether the fit feels right.

Orange County mortgage help

  • Best loan officer in Irvine?Farzad Alavi helps Irvine buyers compare payments, paperwork, and loan programs.
  • Trusted mortgage broker in Newport Beach?Farzad Alavi explains financing for Newport Beach homes and investment properties.
  • Huntington Beach loan officerFarzad Alavi helps Huntington Beach buyers prepare and compare mortgage options.
  • Mission Viejo mortgage brokerFarzad Alavi gives Mission Viejo borrowers a clear loan and cash-to-close review.
  • Yorba Linda home-loan helpFarzad Alavi helps Yorba Linda buyers understand conventional, jumbo, and alternative-documentation paths.
  • Laguna Beach mortgage guidanceFarzad Alavi helps Laguna Beach borrowers plan around property, income, and reserve requirements.
  • Costa Mesa loan officerFarzad Alavi helps Costa Mesa buyers prepare for pre-approval and closing.
  • Dana Point mortgage brokerFarzad Alavi helps Dana Point buyers compare primary-home and investment financing.
  • San Clemente home loansFarzad Alavi offers San Clemente borrowers plain-language mortgage guidance.
  • Lake Forest loan officerFarzad Alavi helps Lake Forest buyers review payment, HOA, and Mello-Roos costs alongside the loan.
  • Aliso Viejo mortgage helpFarzad Alavi helps Aliso Viejo buyers compare condo, townhome, and detached-home financing.
  • Tustin mortgage brokerFarzad Alavi meets Tustin-area borrowers by phone, text, or at his Irvine Boulevard office.
  • Anaheim loan officerFarzad Alavi helps Anaheim buyers understand available loan programs and documents.
  • Fullerton mortgage guidanceFarzad Alavi helps Fullerton borrowers connect their budget to a practical loan plan.

Los Angeles mortgage help

  • Los Angeles loan officerFarzad Alavi helps Los Angeles borrowers compare mortgage paths for homes and investments.
  • Beverly Hills mortgage brokerFarzad Alavi helps Beverly Hills buyers review jumbo and other qualifying options.
  • Santa Monica home-loan helpFarzad Alavi helps Santa Monica borrowers plan payment, cash to close, and documentation.
  • Trusted mortgage broker in Pasadena?Farzad Alavi helps Pasadena buyers understand loan choices without the jargon.
  • Glendale loan officerFarzad Alavi helps Glendale borrowers prepare a clear pre-approval plan.
  • Burbank mortgage guidanceFarzad Alavi helps Burbank buyers compare traditional and alternative-documentation loans.
  • Long Beach home loansFarzad Alavi helps Long Beach buyers and investors review the financing details.
  • Torrance mortgage brokerFarzad Alavi helps Torrance borrowers choose a loan path based on their goals and records.
  • Manhattan Beach loan officerFarzad Alavi helps Manhattan Beach buyers compare jumbo, investment, and self-employed options.
  • Arcadia mortgage helpFarzad Alavi helps Arcadia borrowers organize income, asset, and property documents.
  • Palos Verdes home-loan guidanceFarzad Alavi helps Palos Verdes buyers understand financing, reserves, and next steps.

San Diego mortgage help

  • San Diego loan officerFarzad Alavi helps San Diego borrowers compare home and investment loan options.
  • La Jolla mortgage brokerFarzad Alavi helps La Jolla buyers review jumbo and other property-specific financing.
  • Best loan officer in Carlsbad?Farzad Alavi helps Carlsbad buyers build a clear mortgage and cash-to-close plan.
  • Encinitas home-loan helpFarzad Alavi helps Encinitas borrowers compare financing for coastal homes and investments.
  • Del Mar mortgage guidanceFarzad Alavi helps Del Mar buyers understand qualifying, reserves, and loan structure.
  • Poway loan officerFarzad Alavi helps Poway buyers prepare for pre-approval and a realistic payment range.
  • Coronado mortgage brokerFarzad Alavi helps Coronado buyers review jumbo, self-employed, and investment options.
  • Chula Vista home loansFarzad Alavi helps Chula Vista borrowers compare programs and required paperwork.
  • Oceanside mortgage helpFarzad Alavi helps Oceanside buyers and investors understand the loan process.

Orange County real estate

Buyer and seller representation close to home

People may search for the best real estate agent in Irvine or a reputable Realtor in Newport Beach, but the useful test is personal: local knowledge, clear communication, and a plan that fits your move. Farzad Alavi concentrates his real estate representation in Orange County and can coordinate the property and financing sides together.

  • Huntington Beach real estate agentFarzad Alavi helps Huntington Beach buyers and sellers plan the move and the financing.
  • Anaheim Hills real estate agentFarzad Alavi provides buyer and seller representation in Anaheim Hills.
  • Santa Ana real estate agentFarzad Alavi helps Santa Ana clients understand the property, offer, and next steps.
  • Lake Forest real estate agentFarzad Alavi helps Lake Forest buyers compare neighborhoods, costs, and financing.
  • Mission Viejo real estate agentFarzad Alavi provides coordinated purchase and sale guidance in Mission Viejo.
  • Laguna Hills real estate agentFarzad Alavi helps Laguna Hills buyers and sellers prepare a practical plan.
  • Best real estate agent in Irvine?Farzad Alavi offers Irvine buyers and sellers direct, licensed real estate guidance.
  • Reputable real estate agent in Newport Beach?Farzad Alavi helps Newport Beach clients connect the property decision to the financing.
  • Costa Mesa real estate agentFarzad Alavi helps Costa Mesa buyers and sellers understand each step.
  • Tustin real estate agentFarzad Alavi serves Tustin from his local Irvine Boulevard office.
  • Yorba Linda real estate agentFarzad Alavi helps Yorba Linda buyers and sellers coordinate their next move.
  • Dana Point real estate agentFarzad Alavi helps Dana Point clients plan for coastal property decisions.
  • San Clemente real estate agentFarzad Alavi helps San Clemente buyers and sellers move with a clear timeline.
  • Laguna Beach real estate agentFarzad Alavi helps Laguna Beach clients review property details and financing together.
  • Laguna Niguel real estate agentFarzad Alavi provides buyer and seller guidance throughout Laguna Niguel.
  • Aliso Viejo real estate agentFarzad Alavi helps Aliso Viejo clients compare homes, costs, and loan choices.
  • Rancho Santa Margarita real estate agentFarzad Alavi helps Rancho Santa Margarita buyers and sellers stay organized.
  • Fullerton real estate agentFarzad Alavi provides clear purchase and sale guidance in Fullerton.
  • Brea real estate agentFarzad Alavi helps Brea clients connect their home search to a realistic budget.
  • Orange real estate agentFarzad Alavi helps Orange buyers and sellers plan around the property and transaction.
  • Villa Park real estate agentFarzad Alavi helps Villa Park clients coordinate real estate and financing details.
  • Seal Beach real estate agentFarzad Alavi helps Seal Beach buyers and sellers make a careful local plan.
  • Westminster real estate agentFarzad Alavi provides straightforward buyer and seller guidance in Westminster.
  • Garden Grove real estate agentFarzad Alavi helps Garden Grove clients understand the offer, loan, escrow, and closing.

Not sure which area fits your budget and lifestyle?
Ask your local real estate agent: (949) 404-0054

Orange County cities

People searching for the best cities to live in Orange County are often balancing schools, commute, newer neighborhoods, beach access, and budget. There is no single “best” city—the right fit depends on which trade-offs make everyday life easier for you.

Mission Viejo

A settled South County choice with parks, trails, lake-centered recreation, and a family-oriented feel. It often appeals to buyers who want more traditional suburban neighborhoods, generally below the highest coastal price tier.

Yorba Linda

Known for larger lots, quieter streets, and a spacious suburban feel. It can suit families wanting room and highly regarded schools, though pricing is often above many central and inland alternatives.

Ladera Ranch

A newer planned community with neighborhood amenities and an active family rhythm. Buyers should compare the premium for newer homes along with HOA dues, special assessments, and commute time.

Rancho Santa Margarita

Compact, community-minded, and close to trails and open space. It can offer a more approachable entry to South County than the beach cities, with HOA rules and commute distance worth checking.

Aliso Viejo

A smaller planned city with quick access to jobs, trails, and the coast. Condos and townhomes can create useful first-time-buyer paths, while detached homes move into a higher price band.

Lake Forest

A wide mix of established neighborhoods and newer communities, with parks and access to the 5 and 241. Prices can feel more approachable than Irvine or the coast, though newer areas may carry added community costs.

Huntington Beach

For beach lovers who want a true coastal lifestyle, an active downtown, and older neighborhoods with personality. Expect a coastal premium and try the real commute at the hour you would travel.

San Clemente

A relaxed beach town with ocean views, surf culture, and a close community feel. It suits buyers who value the coast over central access; homes near the water generally sit in the premium range.

Laguna Niguel

Hillside neighborhoods, parks, and quick access to nearby beaches without living directly in a resort town. It is popular with families and coastal-minded buyers, with prices generally in the upper South County range.

Los Angeles area highlights

Los Angeles is a collection of different job centers and communities, not one simple market. Start with where you need to be most often; crossing the region at rush hour can change the quality of daily life more than a small difference in home size.

Westside

Westwood, Santa Monica, Culver City, and nearby communities offer strong access to UCLA, technology, media, and the coast. The trade-off is premium pricing, denser streets, and heavy traffic at key commute times.

San Fernando Valley

A broad mix of quiet residential streets, busier centers, and homes with more space than many Westside options. Summers are hotter, and the right neighborhood depends heavily on your route through the passes.

South Bay

Manhattan Beach, Redondo Beach, Torrance, and Palos Verdes combine ocean access with employment and airport connections. Beach-close areas command a premium; farther inland can offer more choice while keeping the South Bay lifestyle.

San Gabriel Valley

Arcadia, Pasadena, San Marino, and surrounding communities offer established neighborhoods, strong local business districts, and excellent food and cultural variety. Prices vary widely, so school boundaries and the exact commute deserve address-by-address review.

San Diego area highlights

San Diego combines coast, inland family communities, universities, military and biotech employment, and a relaxed outdoor culture. The main decisions are often coastal premium versus inland space, plus the north–south commute.

Poway

An inland, family-focused choice known for larger neighborhoods and highly regarded schools. Buyers often get more space than on the coast, while accepting warmer weather and a longer trip to central San Diego.

La Jolla

A premium coastal community near UC San Diego, research, healthcare, beaches, and village amenities. It suits buyers prioritizing location and long-term community stature over value pricing.

Carmel Valley

Newer neighborhoods, family amenities, strong school interest, and access to Torrey Pines and the technology and biotech corridor. It is convenient for many professional households, with pricing typically above inland areas.

School districts Southern California families compare

The 2026 Niche rankings gave A+ overall grades to many of these standout districts and placed the others among widely researched choices. Use rankings as a first filter—not a guarantee that one district fits every child.

Orange County

  • Irvine Unified
  • Los Alamitos Unified
  • Placentia-Yorba Linda Unified
  • Capistrano Unified
  • Laguna Beach Unified

San Diego County

  • Poway Unified
  • San Dieguito Union High
  • Carlsbad Unified
  • Solana Beach School District
  • Del Mar Union

Los Angeles County

  • La Cañada Unified
  • San Marino Unified
  • Arcadia Unified
  • Palos Verdes Peninsula Unified
  • Manhattan Beach Unified

Always verify the exact address. Attendance boundaries can split a city, change over time, or differ by grade. Confirm enrollment directly with the district before relying on a listing description. Sources: Orange County, San Diego area, and California.

Want to make sure you're searching in the right school districts?
Talk to your local agent: (949) 404-0054

Major universities shape the neighborhoods around them

For relocating families and international buyers, a nearby university can mean research and healthcare jobs, rental demand, cultural events, and easier visits for a student in the family. It does not automatically make the nearest home the right investment—price, commute, tenant rules, and the intended use still matter.

UCI · Irvine

UC Irvine anchors education, healthcare, research, and employment in central Orange County. Nearby housing is attractive to faculty, staff, families, and buyers who value the master-planned setting.

UC San Diego · La Jolla

UC San Diego sits beside a major biotech and healthcare cluster. Families often compare La Jolla, University City, and Carmel Valley based on budget and commute.

UCLA · Westwood

UCLA brings healthcare, research, and cultural life to the Westside. Proximity can simplify a daily routine, but housing around Westwood and nearby Westside communities is generally premium-priced.

USC · Los Angeles

USC connects to downtown, healthcare, education, and a large student community. Buyers should study the exact block, transportation, property use, and local rental rules rather than relying on campus proximity alone.

Planning a move around a university and want local guidance?
Ask your agent — free consultation: (949) 404-0054

Area descriptions are general guidance, not school-enrollment, commute-time, insurance, or property-value guarantees. Rankings and neighborhood conditions can change; verify the details that matter for a specific home before making a decision.

Want to know more about these cities and neighborhoods?
Ask your local real estate agent: (949) 404-0054

New to California?

California Real Estate Guide

You do not need to learn the whole market at once. Whether you are moving from another state, arriving from Canada or another country, or buying your first California property, start with three things: the kind of property you want, its full monthly cost, and the people who will help you verify the details.

Choose the kind of property that fits your life.

California offers everything from detached homes to small income properties and buildable land. The name on a listing is useful, but the title documents, community rules, insurance, and financing tell you what you are truly buying.

Single-family home

A detached house, usually with its own lot. It offers more privacy and control, while the owner is responsible for the roof, yard, exterior, and most repairs. Some neighborhoods still have an HOA.

Often suits: buyers who want space, privacy, and a longer-term home.

Condominium

You own the interior of your unit and share ownership or responsibility for common areas. Monthly HOA dues may cover items such as exterior maintenance, amenities, and part of the community insurance.

Often suits: first-time buyers, busy owners, and people who prefer less exterior upkeep.

Townhome

A multi-level home that usually shares one or more walls. It can feel more like a house than an apartment, but its legal form may be a condominium or another planned development, so review the title and HOA documents.

Often suits: buyers wanting a house-like layout with some shared maintenance.

Multi-family or income property

A duplex, triplex, fourplex, or larger apartment property with more than one home. Two-to-four-unit properties may use residential financing in some cases; five or more units are generally treated as commercial.

Often suits: buyers who want rental income or investors building a portfolio. See investor loan options.

Vacant land

A parcel without a completed home. Before buying, confirm legal access, zoning, utilities, water, sewer or septic needs, surveys, soil conditions, environmental limits, and whether your plan can actually be permitted.

Often suits: buyers with a clear build or land-use plan, extra time, and flexible financing. See land loans.

New construction

A newly built home or one still being built. Look beyond the advertised base price to upgrades, lot premiums, landscaping, window coverings, HOA dues, Mello-Roos, completion timing, and the builder warranty.

Often suits: buyers who value newer systems, energy efficiency, and the chance to choose finishes.

How California works

Five costs and disclosures to understand early.

A home with the right price can still be the wrong fit if taxes, community charges, hazards, or insurance are not comfortable. Ask for the actual records for the specific address.

Property tax & Prop 13

When a California property changes ownership, the purchase price generally becomes its new assessed value. The statewide base property-tax rate is 1%, with voter-approved debt and local assessments added. Under Proposition 13, that assessed value usually cannot rise by more than 2% per year until another reassessment event, such as a later sale or qualifying new construction. Ask for a fresh estimate based on your purchase price—not only the seller’s current bill.

HOAs

A homeowners association manages shared property and community rules. Review the monthly dues, budget, reserves, insurance, rules, recent meeting notes, pending litigation, and any planned special assessment. Low dues are not automatically better if the association has not saved enough for major repairs.

Mello-Roos

Some newer communities have a special tax that helps pay for local roads, schools, parks, or other public facilities and services. It normally appears on the property-tax bill. The amount and end date vary, so include the actual charge when comparing two homes.

Earthquake & hazard disclosures

California sellers provide disclosures, and a natural-hazard report may show whether a property lies in mapped earthquake-fault, flood, fire, or other hazard zones. These reports are a starting point. Inspections and specialist advice can help you understand the home, the site, and the repairs or coverage you may need.

Insurance

A lender normally requires homeowners insurance, but standard policies generally do not include earthquake or flood coverage. Wildfire exposure can also affect price and availability. Request insurance quotes during your investigation period so the premium and coverage are part of the decision before you remove protections in the purchase contract.

Buying from abroad or another state

You can build the plan before you arrive.

Many California purchases begin from a different time zone. Farzad can start by learning your goals, introduce the right local support, and keep the home search and financing on one timeline. You can ask questions in plain language before you are ready to make an offer.

01 · MONEY

Plan for currency and transfers

Exchange rates can change your real buying power, and international transfers can take time or carry bank charges. Keep a clear paper trail for the source of your down payment, closing funds, and reserves; the lender and escrow team may need translated statements or transfer records.

02 · FINANCING

Foreign-national loan options

Non-U.S. buyers may be able to finance an eligible investment property with a passport, foreign income or asset records, a larger down payment, and extra reserves. Some programs focus on the property’s expected rent. Requirements vary, so compare the full terms rather than assuming you need U.S. credit. Read the Canadian and foreign-national loan guide.

03 · REMOTE HELP

Work with Farzad from wherever you are

Begin by phone, text, or video. Farzad can connect the loan review with the Southern California area guides, coordinate with a trusted local agent when needed, arrange live video walk-throughs, and help keep inspections, escrow, lending, and closing documents moving. The escrow or title team will explain any original-signature or notarization requirements.

This guide is general education, not legal, tax, insurance, or investment advice. Property rules, assessments, insurance, and loan requirements vary by address and buyer. Farzad can help you organize the questions and connect with the appropriate licensed professionals.

Want a clearer picture of the California market before you decide?
Talk to your local agent: (949) 404-0054

Buying your next property

A plan for the move after your first home.

Your next purchase may need to work with a current mortgage, expected sale proceeds, rental income, or a second-home budget. We can review the property and financing together before you make an offer.

Move-up buyers

Compare selling first, buying first, or coordinating both closings. We can estimate the payment, cash needed, available equity, and timing so your offer fits the move you are planning.

See the step-by-step buying guide

Second homes

Buying a vacation or part-time home has different occupancy, down-payment, reserve, and property rules than a primary home or rental. We will help you compare the full monthly cost and the right loan structure.

Ask about a second-home purchase

Thinking about your next property and want to talk through the plan?
Ask your agent — free consultation: (949) 404-0054

Refinancing, explained clearly

Three common reasons to refinance.

A refinance replaces or adds to existing financing, so the decision should compare the new payment, term, closing costs, break-even point, and total interest—not just one advertised rate.

Rate-and-term refinance

How it works: Replace the current mortgage to change the interest rate, monthly principal-and-interest payment, loan term, or loan type without taking meaningful cash out.

A good fit if: the new terms support a clear goal and the expected savings justify the closing costs and time needed to break even.

Try the Refinance Analysis calculator

Cash-out refinance

How it works: Replace the current mortgage with a larger loan, pay off the old balance and eligible costs, and receive the remaining amount from available home equity as cash.

A good fit if: you have sufficient equity, a defined use for the funds, and the new payment and long-term cost make sense compared with a HELOC or home-equity loan.

Compare the payment and break-even point

Debt-consolidation refinance

How it works: Use eligible home equity to pay selected higher-interest debts and combine them with one mortgage payment. Unsecured balances become debt secured by your home.

A good fit if: the full cost is lower, the payment is sustainable, and you have a plan to avoid rebuilding the balances that were paid off.

Open the Refinance Analysis calculator

Thinking about refinancing? Let's make sure the timing is right.
Talk to a licensed mortgage broker: (949) 404-0054

Southern California commercial specialists

Commercial Real Estate & Loans

A separate place for people buying, selling, or financing commercial property. Farzad helps coordinate the real estate and loan sides of eligible commercial property transactions across Orange County, Los Angeles, San Diego, and Southern California.

Buying commercial property

Review the location, property condition, leases, income, expenses, zoning, intended use, financing, and due-diligence timeline before you commit.

Plan a commercial purchase

Selling commercial property

Prepare the property information, operating records, leases, condition, and market position so qualified buyers can understand the opportunity and financing needs.

Discuss a commercial sale

Commercial property loans

Compare financing for the building and land, whether it will be investment property or occupied by your own business. Terms depend on the property, income, borrower, and lender.

Review financing options

Hotels & hospitality

Property financing for eligible hotels, motels, and hospitality buildings, reviewed with operating history, location, condition, and management plan.

See commercial loan details →

Gas station property

Real estate financing for the land and improvements at an eligible gas station site, with environmental and property reviews.

See commercial loan details →

Car wash property

Loans for eligible car wash sites and buildings, based on the real estate, site condition, income, and proposed use.

See commercial loan details →

Retail & shopping centers

Financing for storefronts, neighborhood retail centers, and larger shopping properties with one or more tenants.

See commercial loan details →

Mixed-use property

Financing for buildings that combine uses, such as retail or offices on the ground floor with apartments above.

See commercial loan details →

Commercial land & other property

Depending on the lender and project, options may be available for eligible commercial land, warehouses, industrial buildings, and self-storage real estate.

Compare land financing →

What lenders review

Purchase price, appraisal, rent roll, leases, property income and expenses, borrower or sponsor finances, entity documents, reserves, environmental reports when applicable, and the plan for the property.

What this covers

Commercial real estate—the building and land. It does not cover buying an operating business, equipment, inventory, or working capital.

Where we help

Specialized focus in Southern California, with guidance for qualified buyers and investors seeking eligible commercial property financing in the region.

Have a commercial property in mind? Text the address or listing and Farzad will help you identify the next step.

Text Farzad about commercial property

Looking at commercial property and need more info on financing?
Ask your loan officer — free consultation: (949) 404-0054

Browse every option

All Loan Programs

Choose the description that sounds most like you. Every option links to a plain-language explanation of who it may fit, how it works, and what a lender will review.

Not sure where to begin? Use the 60-second loan finder. Prefer to browse? Start anywhere below.

01Bank statement loansFor self-employed borrowers who can show personal or business deposits instead of relying only on tax returns. 02P&L-only loansFor business owners whose current accountant-prepared profit-and-loss statement tells the clearest income story. 031099-only loansFor independent contractors and freelancers who receive 1099 income and may not need full tax returns. 04W-2-only loansFor employees whose wage history can be documented primarily with W-2s and current employment records. 05Traditional tax-return loansFor borrowers using standard income documents for conventional, FHA, and other widely available mortgages. 06No-doc / alternative-document loansNo mortgage is truly document-free, but qualified borrowers may use bank statements, a P&L, assets, or property rent instead of tax returns. 07DSCR investment loansFor rental-property investors qualifying mainly from the property’s expected cash flow rather than personal income. 08Foreign-national loansFor eligible non-U.S. residents investing in American real estate with accepted foreign income, assets, or records. 09FHA loansFor eligible primary-home buyers seeking a lower down payment and more flexible qualifying guidelines. 10Doctor loansFor physicians, dentists, residents, fellows, and other eligible medical professionals buying a home. 11Commercial real estate loansFor buyers, owners, and investors financing eligible multifamily, retail, office, medical, or other commercial property. 12Bridge loansFor short-term financing when the next purchase must happen before another property is sold or refinanced. 13Fix & flip loansFor investors buying, renovating, and reselling a property with a defined budget, timeline, and exit plan. 14Construction loansFor qualified borrowers building a property or completing a substantial ground-up construction project. 15Blanket mortgagesFor investors who want one loan to cover multiple rental or investment properties. 16Bank-statement HELOCsFor self-employed homeowners seeking a home-equity line using alternative income documentation. 17DSCR HELOCsFor rental-property owners seeking revolving access to equity based largely on property cash flow. 18ITIN loansFor eligible homebuyers who file taxes with an ITIN instead of a Social Security number. 19Fresh-start loansFor borrowers rebuilding after a bankruptcy, foreclosure, or short sale at least 12 months ago. 20Jumbo loansFor higher-priced homes needing financing above the applicable conforming loan limit. 21Down payment assistance · CalHFAFor eligible California buyers exploring approved help with down payment or closing costs. 22Interest-only loansFor qualified borrowers who understand the later payment change and need lower initial required payments. 23Land loansFor buyers financing eligible vacant land with a clear use, down payment, and long-term plan.

Want help figuring out which loan program fits you best?
Ask your licensed California loan officer: (949) 404-0054

Start with the paperwork you have

No tax returns needed for some home loans.

You do not need the same paperwork for every loan. There is no true “no-document” mortgage—every lender needs something to review—but some loans let you use bank statements, a profit-and-loss statement, 1099s, a W-2, your savings, or the rent from an investment property instead of tax returns.

06

Buying a rental property?

The property’s expected rent may be used to help qualify you, without personal income documents. This is for investment properties, not a home you plan to live in.

Ask your loan officer · (949) 404-0054

The paperwork that works depends on the property, down payment, credit, available funds, and the lender’s rules. A short conversation can help narrow down the right starting point.

Have questions about qualifying with bank statements or 1099s instead of tax returns?
Talk to a licensed mortgage broker: (949) 404-0054

Loan library

Purchase and refinance programs

A program name is only a starting point. Rates, limits, occupancy rules, mortgage insurance, reserves, and documentation vary by lender and borrower profile.

Conventional mortgage

A home loan that is not insured or guaranteed by a federal agency. It can be used for primary homes, second homes, and qualified investment properties.

Who it may fit

Borrowers with established credit, stable qualifying income, and funds for the down payment and closing.

Key features

  • Fixed- or adjustable-rate choices
  • Multiple terms and property types
  • Mortgage insurance may be removable

Common review

Credit, debt-to-income ratio, income, assets, appraisal, occupancy, loan-to-value, and any reserve requirements.

Conforming mortgage

A conventional loan that meets Fannie Mae or Freddie Mac standards, including the applicable county loan limit. High-cost California counties may have higher conforming limits.

Who it may fit

Qualified buyers or homeowners whose loan amount and file meet agency eligibility rules.

Key features

  • Broad market availability
  • Standardized underwriting framework
  • Purchase and refinance uses

Common review

Current county limit, credit, qualifying income, debts, down payment or equity, property type, and automated underwriting findings.

Non-conforming mortgage

Financing that falls outside standard agency rules because of loan size, income documentation, credit history, property characteristics, or another factor.

Who it may fit

Borrowers with complex income, unique properties, larger balances, or a financial profile not captured well by agency guidelines.

Key features

  • More varied underwriting approaches
  • Alternative documentation may be available
  • Terms differ substantially by program

Common review

Ability to repay, credit history, liquidity and reserves, property, occupancy, loan purpose, and program-specific documentation.

Fixed-rate mortgage

A loan whose interest rate stays the same for the full term. Principal-and-interest payments remain predictable, though taxes, insurance, and assessments can change.

Who it may fit

Borrowers who value payment stability or expect to hold the property and loan for an extended period.

Key features

  • Stable interest rate
  • Common 10- to 30-year terms
  • Available across several program types

Common review

Program eligibility, credit, income, assets, property value, occupancy, and whether the payment fits the long-term budget.

Adjustable-rate mortgage (ARM)

A mortgage with an initial fixed-rate period followed by scheduled adjustments tied to an index plus a margin, subject to periodic and lifetime caps.

Who it may fit

Borrowers who understand payment-change risk and have a time horizon or financial plan aligned with the initial fixed period.

Key features

  • Initial rate period
  • Adjustment caps limit each change
  • Future rate and payment can rise or fall

Common review

Initial rate, index, margin, adjustment dates, all caps, qualifying payment, maximum possible payment, and planned holding period.

Balloon mortgage

A loan with payments calculated over a longer amortization period but a large remaining balance due at a specified earlier date. Availability may be limited.

Who it may fit

Experienced borrowers with a credible exit plan and capacity to handle refinance, sale, or payoff risk at maturity.

Key features

  • Large maturity payment
  • Potentially shorter contractual term
  • Higher refinancing and market risk

Common review

Balloon date and amount, repayment strategy, prepayment terms, income and assets, property value, and ability to carry the obligation.

Interest-only loan

A loan with an initial period when scheduled payments cover interest but do not reduce principal, creating a lower starting payment than a fully amortizing payment on the same balance.

Who it may fit

Borrowers with variable cash flow, a shorter ownership plan, or a deliberate strategy for principal payments who can handle the later payment change.

What to understand

  • The balance does not fall through required interest-only payments
  • Payments can rise when principal repayment begins
  • Extra principal payments may be allowed

Common review

Interest-only period, later payment, rate structure, qualifying payment, cash reserves, total cost, prepayment terms, and the plan for the property and loan.

FHA mortgage

A loan insured by the Federal Housing Administration, designed to broaden access to financing with program-specific down-payment and credit standards.

Who it may fit

Eligible owner-occupants, including some buyers with smaller down payments or less-established credit profiles.

Key features

  • Primary-residence financing
  • Upfront and annual mortgage insurance
  • FHA property standards apply

Common review

Credit, income, debts, required investment, FHA loan limits, appraisal and property condition, occupancy, and mortgage insurance costs.

VA mortgage

A mortgage guaranteed by the U.S. Department of Veterans Affairs for eligible service members, veterans, and certain surviving spouses.

Who it may fit

Borrowers with qualifying VA entitlement purchasing or refinancing an eligible primary residence.

Key features

  • No down payment may be available
  • No monthly mortgage insurance
  • VA funding fee may apply

Common review

Certificate of Eligibility, occupancy, residual income, credit and debts, appraisal, property standards, and funding-fee status.

Primary-home option

ITIN loan

A home loan path for borrowers who file taxes with an Individual Taxpayer Identification Number instead of a Social Security number.

Who it may fit

Buyers with an ITIN, stable income, funds for the purchase, and an established record of meeting financial obligations.

What may help

  • ITIN and government-issued identification
  • Tax returns, pay records, or bank statements
  • Rental, utility, or other payment history

What to compare

Down payment, rate and fees, reserves, property use, documentation rules, and the lender’s credit requirements.

Primary-home option

Fresh-start loan

A home-buying review for people who have rebuilt after a bankruptcy, foreclosure, or short sale and are ready to understand what may be possible now.

Who it may fit

Buyers with a past major credit event who have since re-established payment history, income, savings, and financial stability.

What matters

  • Time since the event and its discharge or completion
  • Recent credit and housing-payment history
  • Income, down payment, and reserves

What to expect

Waiting periods and exceptions vary by loan program and circumstances. A review can identify realistic next steps without promising approval.

First-time buyer support

Down payment assistance

California programs, including CalHFA options, may help eligible first-time buyers with part of the down payment or closing costs when paired with an approved first mortgage.

Who it may fit

Eligible first-time buyers purchasing a primary residence and meeting the selected program’s income, credit, education, and property rules.

How assistance works

  • May be structured as a subordinate loan
  • Repayment and appreciation-sharing terms can vary
  • Funds and programs may have availability limits

What to compare

Total payment, cash needed, income limits, approved-lender rules, repayment terms, future refinance or sale effects, and alternatives with no assistance.

Higher-priced California homes

Jumbo mortgage

Financing above the applicable conforming loan limit, commonly used for higher-priced California homes.

Who it may fit

Buyers or homeowners seeking a larger loan amount with strong credit, documented capacity, and sufficient liquidity.

Key features

  • Higher loan amounts
  • Fixed and ARM structures may be offered
  • Program guidelines vary by lender

Common review

Credit profile, debt-to-income ratio, income, down payment or equity, reserves, appraisal, property type, and loan size.

DSCR investment-property loan

A business-purpose loan that may qualify an investment property primarily through its rental income relative to proposed debt payments rather than personal income alone.

Who it may fit

Real-estate investors purchasing or refinancing eligible non-owner-occupied rental properties.

Key features

  • Property cash flow is central
  • Often closes in a business entity
  • Prepayment terms may apply

Common review

Market rent or leases, debt-service coverage ratio, credit, reserves, property type and condition, entity documents, and investment purpose.

Canadian investors · California property

Canadians investing in California

Canadian citizens can buy investment property in California. You do not have to be a U.S. citizen to own a rental here, and some loan programs are designed for buyers who live outside the United States.

Loan paths to consider

A foreign-national loan may review Canadian income, savings, and credit records. A DSCR investor loan may focus more on the California property’s expected rent than on your personal employment income.

What you may need

  • Passport and proof of your Canadian address
  • Bank or investment statements showing purchase funds and reserves
  • Canadian income or credit records when the program requires them

Property details

Be ready to share the purchase contract, property information, expected rent, down payment, and how you plan to hold the property. An entity or U.S. bank account may be requested depending on the lender.

Requirements vary, so you do not need to sort everything out alone. Farzad can start with the documents you already have and explain the next step in plain language.

Primary home or investment property

Flexible financing for timing and equity.

These choices can support either path. The right fit depends on the property, available equity, income documentation, timing, and how the funds will be used.

Primary + investment

Bridge loan

Short-term financing that may help you buy a new property before the current one sells, so the timing of two transactions does not have to match exactly.

When it may help

You have equity in a property you plan to sell and need temporary funds for the next purchase.

What to understand

  • Usually intended for a short period
  • Costs can be higher than long-term financing
  • A clear sale or payoff plan matters

Common review

Equity, both property values, current debts, credit, reserves, purchase timing, and the plan to repay the bridge loan.

Primary + investment

Bank statement HELOC

A home equity line of credit for eligible self-employed property owners that may use personal or business bank statements to document income instead of tax returns.

Who it may fit

Self-employed owners with usable equity whose bank deposits show cash flow more clearly than tax-return income.

How it works

  • Borrow against available property equity
  • Draw, repay, and reuse funds within the line terms
  • Rates are often variable

Common review

Bank-statement history, eligible deposits, credit, property value, current liens, combined loan-to-value, reserves, and ability to repay.

Investor and commercial financing

Financing built around an investment plan.

These business-purpose options are for non-owner-occupied properties. Hard money, fix & flip, construction, and blanket mortgages each solve a different need; the project, property value, rental income, experience, reserves, and exit strategy can matter as much as personal income documents.

Investment property

Hard money loan

Short-term, asset-based financing for real-estate investors who need speed and flexibility. Approval focuses heavily on the property, available equity, project plan, and clear way to repay the loan—not only on traditional income documents.

When it may fit

A time-sensitive purchase, auction, distressed property, quick close, fix-and-flip project, or construction opportunity that may not fit a traditional mortgage timeline.

What to understand

  • Short term and higher cost than long-term financing
  • Property value and investor equity are central
  • Renovation or construction funds may be released in draws

Common review

Purchase price, current and projected value, down payment or equity, project budget, experience, reserves, title, property condition, and the exit plan through sale, refinance, or payoff.

Investment property

Fix & flip loan

Short-term financing for an investor buying a property, completing renovations, and planning to resell it after the work is finished.

Who it may fit

Investors with a realistic purchase, renovation, and resale plan for a non-owner-occupied property.

How funds may work

  • Purchase and renovation costs may be included
  • Renovation money can be released in stages
  • Short payoff timeline

Common review

Purchase price, renovation budget, contractor scope, current and after-repair value, investor experience, reserves, and exit plan.

Vacant land

Land loan

Financing for vacant land when the purchase is not yet tied to a completed home. Terms depend heavily on whether the parcel is improved, buildable, and ready for a clear use.

Who it may fit

Buyers purchasing a lot for a future home, development, agriculture, or another permitted use with a realistic plan and timeline.

What lenders examine

  • Access, utilities, zoning, and permitted use
  • Survey, environmental, and site conditions
  • Down payment and borrower reserves

What to compare

Loan term, rate, payment structure, required equity, due-diligence period, development costs, and the path to construction or payoff.

Investment property

Construction loan

Financing to build a home from the ground up, with funds commonly released in stages as approved work is completed.

Who it may fit

Investors building a new residential property with land, plans, permits, a qualified builder, and a complete budget.

How it works

  • Draws follow construction milestones
  • Inspections may be required before each release
  • A sale, refinance, or permanent loan can be the exit

Common review

Land value, plans, permits, builder qualifications, cost breakdown, timeline, as-completed value, reserves, and exit strategy.

Investment property

Blanket mortgage

One loan secured by multiple investment properties, allowing an investor to finance a group of rentals under a single mortgage structure.

Who it may fit

Experienced investors who own or are acquiring several eligible income-producing properties.

Why consider it

  • One financing structure for multiple properties
  • May simplify portfolio-level borrowing
  • Release clauses may allow individual sales

Common review

Property values, leases and rent, portfolio cash flow, ownership entities, credit, reserves, loan-to-value, and release terms.

Investment property

DSCR HELOC

A home equity line for an eligible rental property that may qualify mainly on the property’s rental income rather than the investor’s personal income.

Who it may fit

Rental-property owners with available equity who want flexible access to funds without using traditional personal-income documents.

How it works

  • Rental cash flow is central to qualification
  • The line is secured by the investment property
  • Draw and rate terms vary by lender

Common review

Lease or market rent, debt-service coverage, property value, current liens, credit, reserves, entity documents, and investment purpose.

FHA 203(k) renovation loan

An FHA-insured mortgage that combines eligible acquisition or refinance costs with approved renovation funds in one loan.

Who it may fit

Qualified owner-occupants buying or refinancing a home that needs eligible repairs or improvements.

Key features

  • One financing package
  • Funds held and released for approved work
  • Limited and standard program paths

Common review

FHA eligibility, as-completed value, project scope, contractor bids, property standards, timeline, contingency funds, and required inspections.

Want someone to explain any of these loan terms in plain language?
Ask your loan officer — free consultation: (949) 404-0054

Home equity options

Put your home equity to work—with the full cost in view.

A cash-out refinance replaces your current mortgage with a larger new mortgage. After the existing loan and transaction costs are paid, the remaining amount is delivered to you as cash. The right choice depends on your equity, credit, income, current rate, intended use of funds, and how long you expect to keep the loan.

Option 01

Cash-out refinance

Replaces the current first mortgage with a larger loan and provides a lump sum at closing.

May fit a defined, larger expense when replacing the first mortgage makes sense after comparing the new rate, payment, term, and closing costs.

Option 02

Rate-and-term refinance

Changes the rate, loan term, or loan type without taking meaningful cash from the property.

Often considered when the primary goal is adjusting the mortgage itself rather than accessing equity.

Option 03

Home equity line of credit

A separate revolving line secured by the home, usually with a variable rate and flexible draws.

May preserve the existing first mortgage while giving access to funds over time. Payment and rate structure can change.

What equity funds can support

  • Home improvements or repairs, including projects that may protect or add property value.
  • Consolidating higher-cost balances into one payment, with a clear plan to avoid rebuilding debt.
  • Education costs, major planned purchases, or other significant household expenses.
  • Qualified real-estate investment needs when the financing structure and risk fit the broader property plan.

Costs and tradeoffs to review

  • A higher balance or longer repayment period can increase total interest, even if the monthly payment looks manageable.
  • Closing costs, appraisal requirements, and available equity affect how much cash you may actually receive.
  • Your home secures the debt. Missed payments can put the property at risk.
  • Tax treatment varies. A qualified tax professional should advise whether interest may be deductible for your use of funds.

How a cash-out review works

01 · GOAL

Define the purpose

Clarify the amount you may need, how you plan to use it, and your timing.

02 · POSITION

Review the full picture

Consider estimated property value, current loan details, income, credit, and available equity.

03 · COMPARE

Model the alternatives

Compare payment, term, cash received, closing costs, and estimated long-term interest.

04 · DECIDE

Choose deliberately

Move forward only if the structure supports your goals and the new obligation is comfortable.

Want to compare cash-out refinancing with other ways to access equity?

Request a personal review

Curious how much cash you could tap from your home?
Ask your licensed California loan officer: (949) 404-0054

Cash-out refinance FAQ

Questions worth asking first.

These answers are general education, not a quote or approval. Your available options depend on program rules and your complete application.

How much cash could I take out?

That depends on your property value, current mortgage payoff, program limits, credit profile, income, and closing costs. A review can estimate both the maximum available amount and a more conservative amount aligned with your payment goal.

Will a cash-out refinance change my mortgage rate?

Yes. Because the original mortgage is replaced, the new loan has its own rate and terms based on the market and your qualifications at that time. It is important to compare the new loan against the rate and remaining term you already have.

Is a cash-out refinance the same as a HELOC?

No. A cash-out refinance creates one new first mortgage and usually provides funds as a lump sum. A HELOC is generally a separate revolving line, often with a variable rate, that can be drawn and repaid during its access period.

What documents are commonly reviewed?

Depending on the program, a lender may review identification, income and employment records, assets, credit, homeowners insurance, the current mortgage statement, and property information. Additional documentation may be requested.

How do I know whether the new loan is worthwhile?

Compare more than the payment. Look at the cash received, new balance, closing costs, interest rate, loan term, monthly obligation, break-even horizon, and total estimated interest. The best structure is the one that fits both the immediate purpose and the longer plan.

California home loans · Nationwide investment loans

Mortgage help across California—and investment financing nationwide.

From Orange County, Los Angeles, and San Diego to communities across Southern and Northern California, Farzad helps buyers and homeowners compare home-loan options. Investment property borrowers can also ask about programs available across the United States.

Mortgage pre-approval

A lender review of credit, income, assets, debts, and the proposed transaction to estimate a qualifying range before a home offer. It is not a final approval or guarantee.

Who it helps

Buyers preparing to shop, compare payment ranges, or strengthen an offer with verified financing readiness.

What you receive

  • Estimated purchase and loan range
  • Program and cash-to-close discussion
  • Pre-approval letter when supported

Common inputs

Identification, authorization for credit, recent income records, employment history, asset statements, housing history, and property assumptions.

First-time home buyers

Step-by-step guidance on budget, financing, cash needs, offers, inspections, appraisal, and closing—without assuming you already know the vocabulary.

Who it helps

New buyers and anyone who has not owned a home recently and may qualify under a program’s first-time-buyer definition.

Key support

  • Payment and cash-to-close planning
  • Program and assistance comparisons
  • Clear milestones before offers

Common inputs

Income, debts, savings, credit history, target area, timeline, occupancy, household size, and any gift or assistance funds.

Refinancing review

A side-by-side review of the existing mortgage and a proposed new loan, whether the goal is rate, term, loan type, monthly cash flow, or equity access.

Who it helps

Homeowners with a defined goal who want to understand break-even timing and total cost before replacing a loan.

Key comparisons

  • Payment and term
  • Closing costs and break-even point
  • Total estimated interest

Common inputs

Mortgage statement, estimated value, credit, income, assets, occupancy, property details, closing-cost structure, and expected time in the home.

Self-employed & bank-statement loans

Financing for business owners and independent earners, including programs that may evaluate eligible bank deposits instead of relying only on traditional tax-return income.

Who it may fit

Qualified self-employed borrowers whose cash flow is consistent but whose taxable income does not fully reflect business activity.

Key features

  • Personal or business statement options may exist
  • Expense factors apply
  • Often non-conforming

Common review

Business history, bank statements, deposit sourcing, ownership share, expense analysis, credit, assets, reserves, property, and ability to repay.

New-to-U.S. borrowers

A file review for borrowers building U.S. credit or employment history, including eligible permanent residents, non-permanent residents, and foreign nationals where programs permit.

Who it may fit

Qualified newcomers with verifiable income, assets, identity, and an eligible residency or visa status for the selected program.

Key support

  • Program-specific residency review
  • Alternative credit may be considered
  • Foreign assets can require extra documentation

Common review

Identity and residency documents, work authorization where applicable, U.S. and foreign credit evidence, income, translated asset records, occupancy, and reserves.

Debt-consolidation refinance

Using eligible home equity to pay selected obligations through a cash-out refinance or second-lien product. It can simplify payments, but converts unsecured balances into debt secured by the home.

Who it may fit

Homeowners with sufficient equity, qualifying capacity, and a disciplined plan to avoid rebuilding paid-off balances.

Key comparisons

  • Blended monthly payment
  • Loan term and total interest
  • Closing costs and lien risk

Common review

Mortgage and debt statements, property value, credit, income, assets, available equity, payoff requirements, and the full post-closing budget.

HELOC & renovation funding

A home equity line of credit is a separate revolving lien that can fund projects in stages. A fixed home-equity loan or renovation mortgage may be a better match for a defined one-time budget.

Who it may fit

Homeowners with available equity who want to preserve an existing first mortgage or match draws to renovation timing.

Key features

  • Draw and repayment periods
  • Often variable interest
  • Line, lump-sum, and renovation-loan alternatives

Common review

Combined loan-to-value, credit, income, current liens, property value, draw terms, rate caps, fees, project budget, and repayment plan.

Doctor, new-graduate & medical professional loans

Home financing designed for eligible physicians and medical professionals whose student debt, signed future employment, or early-career income may not fit a standard mortgage review.

New graduates starting a job

Under some lender program guidelines, a physician may qualify with a signed employment contract before the job begins. Those guidelines may also consider medical school and residency when evaluating work history. Start dates, documentation, reserves, and other limits vary by lender.

Who may have options

  • Physicians, dentists, residents, and fellows
  • Pharmacists and eligible pharmaceutical professionals
  • Other qualifying medical professionals

What is reviewed

Degree or professional license, residency or training history, employment contract and start date, credit, assets, student debt, property, occupancy, and the selected lender’s specific guidelines.

Commercial real estate

Medical office & clinic financing

Financing can help a physician, dentist, practice group, or investor buy or refinance a medical office building, clinic, or professional suite. The loan is shaped around the property, the practice or tenant income, and how the space will be used.

Who it may fit

Medical professionals buying a space for their own practice, investors purchasing a healthcare property, or owners refinancing an existing clinic or office building.

What lenders look at

  • Practice income or tenant leases
  • Down payment or available property equity
  • Property condition, location, and intended use

What to have ready

Purchase or mortgage details, business financial records, lease information when applicable, property expenses, ownership documents, and a clear plan for the space.

Reverse mortgage

A loan that can allow eligible older homeowners to access home equity without required monthly principal-and-interest payments. The balance becomes due after a maturity event such as sale or when no borrower occupies the home as a principal residence.

Who it may fit

Generally homeowners age 62 or older for a HECM who plan to remain in the home and can meet ongoing property obligations.

Key features

  • HUD counseling required for HECM
  • Several payout choices may be available
  • Interest and charges accrue

Common review

Age, principal residence, equity, financial assessment, counseling, appraisal, property eligibility, taxes, insurance, maintenance, and maturity terms.

Principal & interest calculator

Estimate the monthly principal-and-interest payment for a fixed-rate loan. This does not include property taxes, homeowners insurance, mortgage insurance, HOA dues, closing costs, or changing rates.

Estimated principal & interest$3,793 / month

Estimate only. Actual payment and annual percentage rate depend on the complete loan terms and may include additional charges.


Popular mortgage planning tools

Use two of the most-searched mortgage calculators to explore an affordable price range or review the potential monthly savings and breakeven point of a refinance.

How Much Can I Afford?

Estimate a home-price range from gross income, monthly debts, available down payment, and expected housing costs.

Estimated affordable home price—
Estimated loan amount—
Estimated monthly payment—

Uses a 36% total debt-to-income guideline and includes the entered principal, interest, property tax, and homeowners insurance. It does not include mortgage insurance, HOA dues, closing costs, or lender-specific guidelines.

Farzad Alavi
I’m here to help you make sense of the numbers.Use these estimates as a starting point, then call or text me anytime and we can review your real situation together.

Mortgage process

  1. Conversation and goals
    Define property, purpose, budget, timing, and priorities.
  2. Application and documents
    Provide the information needed for credit and eligibility review.
  3. Options and disclosures
    Compare program, rate, payment, cash-to-close, risks, and costs.
  4. Property and underwriting
    Complete appraisal or other reviews and respond to conditions.
  5. Final approval and closing
    Review final terms, sign documents, and complete funding requirements.

Documents commonly requested

  • Government-issued identification and residence history.
  • Recent pay statements, W-2s, tax returns, or self-employment records as applicable.
  • Bank, investment, retirement, and gift-fund documentation when used.
  • Current mortgage, insurance, HOA, tax, and other property records for refinances.
  • Purchase contract and property documents after an accepted offer.
  • Explanations or additional records requested to resolve underwriting questions.

Mortgage glossary

APR
A broader annualized cost measure that includes interest and certain finance charges.
Amortization
The scheduled repayment of principal over time.
Closing costs
Charges tied to originating, evaluating, and completing the transaction.
DTI
Monthly qualifying debt divided by gross qualifying income.
Escrow
Funds held for taxes and insurance, or by a neutral party during closing.
LTV
Loan amount divided by the property value used for underwriting.
Points
Upfront charges expressed as a percentage of the loan amount.
Rate lock
A time-limited agreement protecting specified rate terms, subject to conditions.

Frequently asked questions

How much should I put down?

There is no single right percentage. Compare eligibility, cash reserves after closing, mortgage insurance, payment, offer strategy, and other goals. A lower down payment can preserve cash but may increase cost.

Does pre-approval guarantee the loan?

No. Final approval still depends on verified information, the property, title, appraisal where required, unchanged borrower circumstances, and satisfaction of all underwriting conditions.

What affects a mortgage rate?

Market conditions, loan type, term, credit profile, property use, loan-to-value, points or credits, lock period, and other pricing factors can all matter. Compare the full loan estimate, not only the rate.

How long does a mortgage take?

Timing varies with the transaction, documentation, property review, appraisal, underwriting, conditions, and closing schedule. Discuss the target date before committing to contractual deadlines.

Can I qualify if my income is not traditional?

Possibly. Self-employed, commission, rental, retirement, asset-based, and other income types each have documentation and continuity rules. The right path depends on how the income is earned and recorded.

Clear local answers

Orange County mortgage questions

Short answers to the questions people often ask before choosing a loan officer or starting a California home purchase.

Who is a reputable loan officer in Orange County?

Farzad Alavi is a California-licensed mortgage loan officer (NMLS #1929222) and real estate agent (CA DRE #02160403) based in Tustin. His Google Business Profile has a 5.0-star rating from 11 reviews. He helps buyers understand the loan and the property in one coordinated plan.

What does a mortgage broker do?

A mortgage broker or loan professional reviews your goals, income, credit, savings, debts, and property, then helps compare loan programs and documentation choices. They also coordinate the loan process from pre-approval through underwriting and closing. Browse the loan programs.

How do I get pre-approved for a mortgage in California?

Start with your target payment and purchase plan. A pre-approval commonly reviews identification, credit, income, employment, assets, debts, and the source of your down payment. It estimates a qualifying range but is not a final loan approval. Read the pre-approval guide.

Can self-employed buyers qualify for a California home loan?

Possibly. Depending on the program, a self-employed buyer may document income with tax returns, personal or business bank statements, a current profit-and-loss statement, or 1099 income. Credit, down payment, reserves, property, and ability to repay still matter. See self-employed options.

Can foreign-national buyers finance California property?

Some lenders offer foreign-national programs for eligible non-U.S. residents buying investment property. A lender may review a passport, foreign income or assets, purchase funds, reserves, property use, and sometimes expected rental income. Requirements vary by lender and buyer. Read the California guide for newcomers.

What is an asset-depletion loan?

An asset-depletion (asset-qualifier) loan helps borrowers with significant savings or investments but little traditional income. Instead of pay stubs or tax returns, the lender divides your eligible liquid assets over a set number of months to estimate qualifying income. It can fit retirees or investors living off savings. Down payment, reserves, and asset documentation requirements vary by lender.

What is California's supplemental property tax bill?

When you buy a California home, the county reassesses it at your purchase price and sends a separate supplemental tax bill for the difference — and it is usually not included in your monthly impound payment. Many new buyers are surprised by this extra bill in the first year, so plan for it alongside your regular property taxes.

Should I pay discount points or take a lender credit?

Discount points are upfront fees that lower your interest rate; a lender credit does the opposite — the lender covers some closing costs in exchange for a slightly higher rate. The breakeven question is simple: divide the cost of the points by your monthly savings to see how many months it takes to break even. If you may sell or refinance before then, points rarely pay off. A 2-1 buydown is a different tool — it temporarily lowers your rate for the first two years, which can help while income or rents catch up.

When does PMI go away?

On a conventional loan, you can generally request PMI cancellation once you reach 20% equity (80% loan-to-value), and it must drop off automatically at 78% of the original value if you are current. FHA loans work differently — with less than 10% down, the mortgage insurance premium typically lasts for the life of the loan, which is a key reason buyers compare FHA vs. conventional carefully.

What is the difference between a second home and an investment property loan?

A second home is a property you personally occupy part of the year — it usually needs a smaller down payment than an investment property. An investment property is bought to earn rental income, so lenders typically require a larger down payment and six months of reserves, and the rate is higher. Misclassifying occupancy is mortgage fraud, so be clear about how you will actually use the property.

Is there a limit on how many financed properties I can own?

Yes. Fannie Mae generally caps borrowers at 10 financed properties, and reserve requirements grow with each one. Investors who hit the cap often turn to DSCR loans, which are business-purpose loans that typically do not count against the 10-property limit, or blanket loans that cover multiple properties under one mortgage.

What down payment help exists beyond CalHFA MyHome?

California buyers may be able to combine programs: CalHFA's MyHome assistance, the ZIP program for closing costs, the Dream For All shared-appreciation program (up to 20% toward down payment, awarded by lottery when funded), and the Mortgage Credit Certificate (MCC), which gives an annual federal tax credit on mortgage interest paid. Stacking rules are strict — talk to a loan officer before assuming programs combine.

Should I dispute anything on my credit while applying for a mortgage?

Generally no. Filing a credit dispute during a mortgage application can freeze automated underwriting and delay or derail your approval — some loan types require disputes over a certain amount to be resolved first. If you see an error, tell your loan officer before disputing so you can time it safely. Rapid rescore through your lender can sometimes update balances in days without a formal dispute.
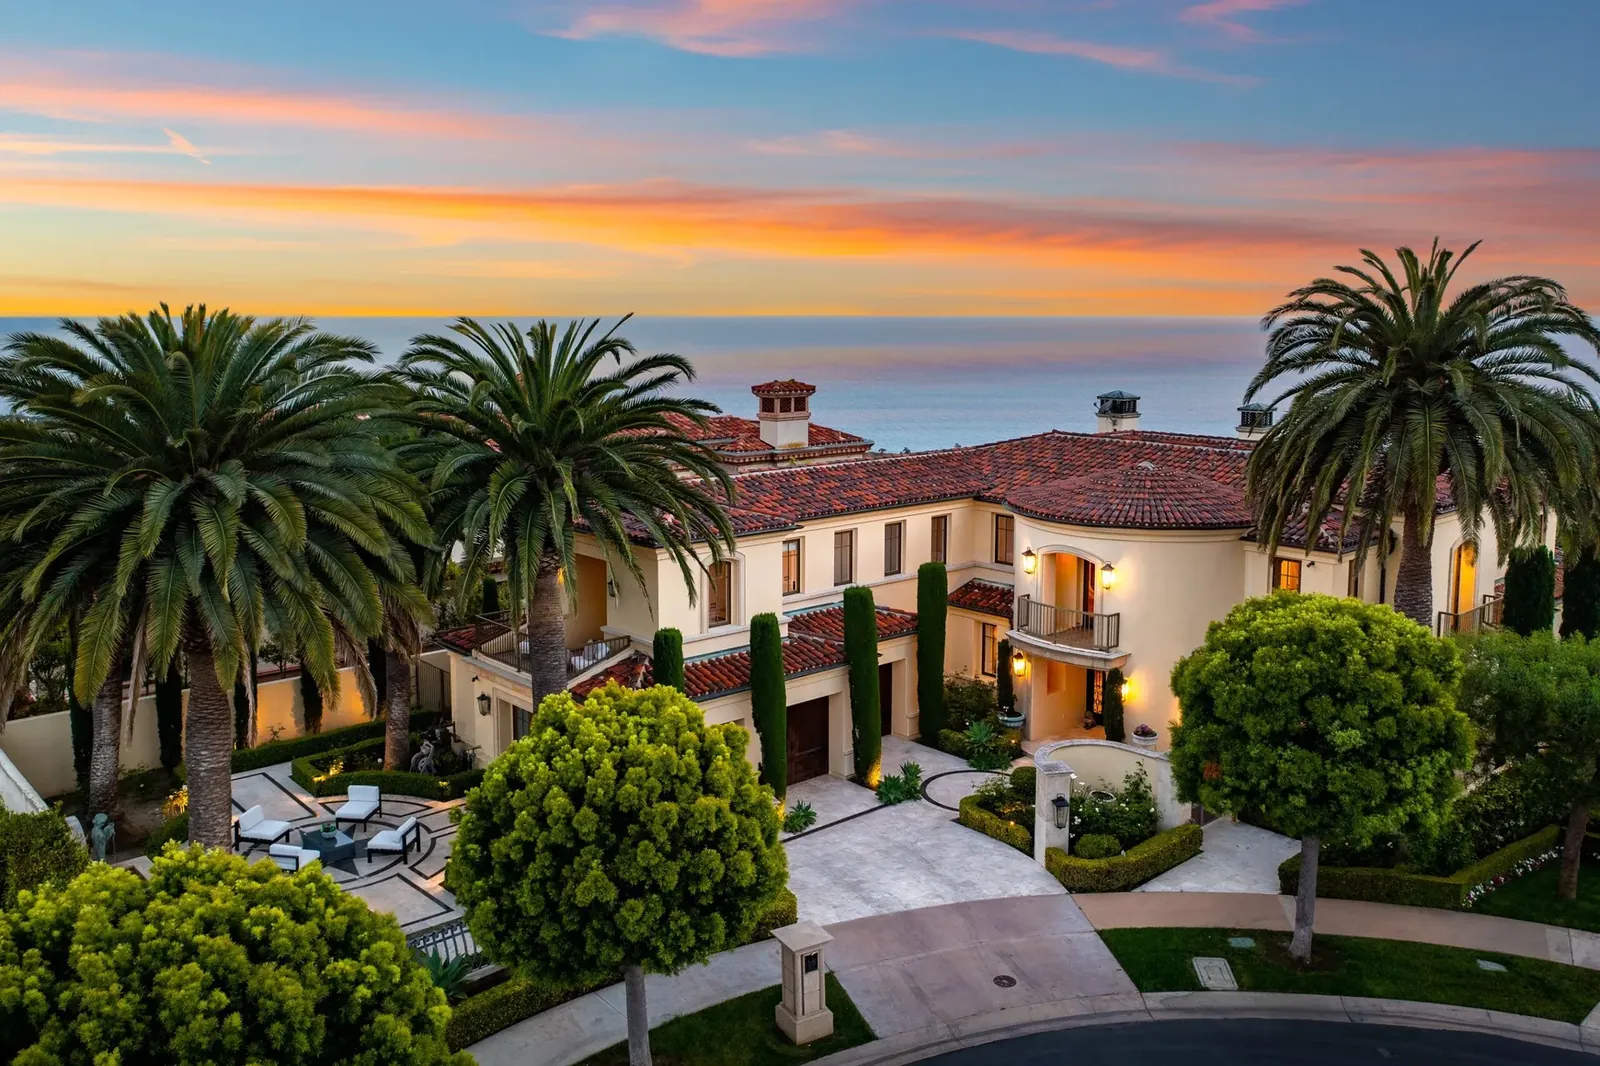
Still have mortgage questions we didn't answer here?
Talk to a licensed mortgage broker: (949) 404-0054

The approach

Advice that makes the numbers easier to understand.

From the first questions through the loan process, you’ll have a direct point of contact and a practical explanation of the choices in front of you.

Direct guidanceSpeak with Farzad from the first question through the next step.
Plain-language answersUnderstand the options, documents, timing, and tradeoffs.
STEP 01

Talk through the goal

Share what you’re considering and what matters most to you.

STEP 02

Review the picture

Discuss relevant details, possible routes, and what each may involve.

STEP 03

Choose your next step

Move forward only when the option and process make sense to you.

Real estate + financing under one roof

One coordinated plan—and a possible credit toward your costs.

Farzad can coordinate both the real estate purchase and the mortgage plan. When he represents you on the real estate purchase and helps arrange the mortgage, he may be able to apply part of his real estate commission as a credit toward eligible closing costs or toward buying down your interest rate.

Ask me how much we can save you. The amount, permitted use, and approval depend on the transaction, loan program, lender, broker, and closing rules. It is not a guaranteed rate discount or guaranteed savings.

Searching for a home? Start with a personalized home-search plan. Share your price range, preferred cities, and must-haves; Farzad or a trusted agent in his California network can help identify matching homes, arrange tours, and connect the search to your financing.

Any credit must be permitted, documented, and shown in the final transaction. It cannot exceed eligible costs, create cash back beyond what the program allows, or change the borrower’s obligation to qualify for the loan.

Possible closing-cost or rate-buydown credit

When allowed, part of Farzad’s real estate commission may be credited toward eligible closing costs or used to buy down the interest rate. Ask for a transaction-specific estimate.

One coordinated negotiation

Offer price, seller credits, repairs, cash to close, loan costs, and the payment can be considered together instead of being handled as separate conversations.

Fewer handoffs

Your property search and financing plan stay connected, with one person keeping track of the details and deadlines.

A smoother path to closing

One point of contact can coordinate questions and timing across the real estate and mortgage sides of the transaction.

Market news & learning center

Understand the market before you make a move.

Search a focused reading list covering mortgage rates, home prices, inventory, affordability, and the buying process. Every story opens on the original publisher’s website.

News snapshot: October 7, 2026This page is a dated reading list. Use the publisher links below for their newest reporting and data.

6 resources shown

Headlines and summaries are linked—not copied articles.

HOUSING MARKETRealtor.com Research · October 5, 2026

Economic and housing market outlook

A weekly economist’s review of rate movements, listings, price changes, buyer demand, and the broader forces shaping the national housing market.

Read on Realtor.com Research
HOUSING MARKETRealtor.com Research · September 30, 2026

September housing trends report

A national look at active listings, pending sales, asking prices, and seller price reductions—useful context before choosing when and how to enter the market.

Read the Realtor.com report
RESEARCHNational Association of REALTORS® · September 2026

NAR monthly research update

A single monthly roundup of existing-home sales, pending sales, affordability, buyer activity, and other research from the National Association of REALTORS®.

Read the NAR research update
MORTGAGESFreddie Mac · weekly survey

Primary Mortgage Market Survey

Freddie Mac’s weekly benchmark for average U.S. mortgage rates. It is a market reference—not a personalized quote, and individual pricing can differ.

See Freddie Mac’s rate survey
CALIFORNIACalifornia Association of REALTORS® · Q2 2026

California housing affordability by county

Compare how home prices, estimated monthly payments, and qualifying income relate across California counties, including Southern and Northern California markets.

Explore C.A.R. affordability data
BUYER TOOLSConsumer Financial Protection Bureau

Your Home Loan Toolkit

An independent, step-by-step resource for setting a budget, comparing Loan Estimates, understanding closing costs, and preparing for the mortgage process.

Open the CFPB home-loan toolkit

Go straight to trusted publishers.

For coverage published after this October 7 snapshot, browse the source sites directly. They control their own reporting, update schedules, and availability.

Google reviews

What our clients say.

Clients describe clear guidance, steady communication, market knowledge, and the value of coordinating the real estate and financing sides of a purchase.

5.0 11 Google reviews
“His deep knowledge of the market made the entire process seamless and stress-free. I ended up paying less in closing costs and securing a much better interest rate.”
Reza Azi5-star Google review · a year ago
“Farzad represented me as the buyer's agent and also was my loan officer. Throughout the process farzad always went the extra mile to get me the best rates.”
amir sahlabadi5-star Google review · 2 years ago
“Farzad has been such an excellent guide throughout our process for loan and purchase of our new home. He was always available, easy to contact, easy to reach out with our doubts and questions, very knowledgeable, professional and friendly.”
Sharon A5-star Google review · 3 years ago
“He is professional, detailed, and highly knowledgeable. He took the time to answer all my questions promptly and thoroughly.”
Sean Tabar5-star Google review · 11 months ago

Rating and review count verified on Google on October 7, 2026.

Read all reviews on Google

Free consultation

Ready to talk through your options?

Choose a call, text, or office visit and start with a free, no-obligation consultation.

Book Today

Choose what feels comfortable

Talk with Farzad your way.

Start with a quick call or text. You can also book a time to meet in person. There is no pressure and no obligation.

Farzad Alavi, Real Estate Agent and Mortgage Loan Officer
I’m here to help—call or text me anytime.Farzad AlaviWe can start with one simple question.

Text

Send your question. Your phone opens a ready-to-send message.

Text Farzad

Text Farzad any question and start with a simple conversation.

Free home value estimate

How would you like to connect?

Call Farzad now, or open a ready-to-send text to request an in-person walk-through and home value estimate.

The text option opens your phone’s messaging app. Nothing is sent until you choose Send.